

As boating season ends, many North Carolina homeowners are getting their boats ready for storage. But before you put your boat away this fall, there’s another important question to ask:
How much protection does your homeowners insurance actually provide for your boat?
Many homeowners are surprised to learn that their homeowners policy may provide only limited coverage for watercraft even when stored in their garage. If your boat is worth significantly more than that limit, you could be leaving a substantial portion of your investment uninsured.
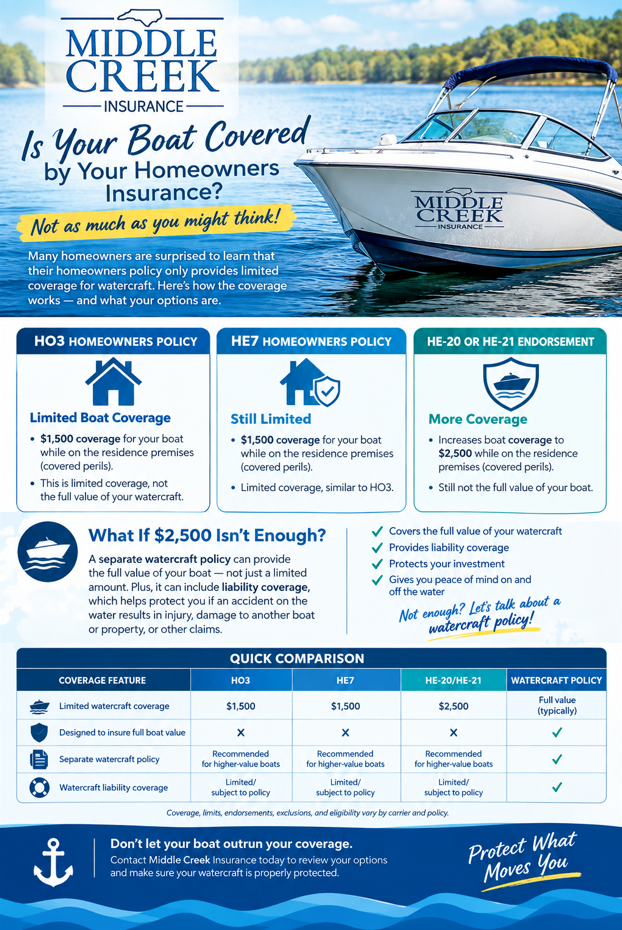
HO3 Homeowners Policy: Limited Boat Coverage
Under an HO3 homeowners policy form, coverage for a boat is generally limited to $1,500 for certain covered perils while the boat is on the residence premises.
That may sound helpful—but consider the value of many boats today. If you own a $15,000, $30,000, or $50,000 boat, a $1,500 limit may fall far short of what you need.
And remember, this is limited coverage, not coverage for the full value of your watercraft.
HE7 Homeowners Policy: Still Limited
An HE7 homeowners policy also provides limited coverage for watercraft, with a $1,500 limit.
What About the HE-20 or HE-21 Endorsement?
Depending on the policy and carrier, adding an HE-20 or HE-21 endorsement can increase the available watercraft coverage to $2,500.
That’s an improvement—but if your boat is worth $20,000 or more, you’re still potentially leaving a significant gap in coverage.
What If $2,500 Isn’t Enough?
That’s where a separate watercraft policy can make a big difference.
A dedicated watercraft policy can be designed to cover the full value of your boat, motor(s), and trailer, rather than relying on the limited watercraft coverage included with your homeowners policy.
Depending on the policy, watercraft insurance can also provide important liability coverage.
That’s particularly important because an accident on the water can involve much more than damage to your boat. You could also be responsible for injuries, damage to another boat or property, or other liability claims.
A Quick Comparison
| Coverage | HO3 | HE7 | HE7 + HE-20/HE-21 |
|---|---|---|---|
| Limited watercraft coverage | $1,500 | $1,500 | $2,500 |
| Designed to insure full boat value | ❌ | ❌ | ❌ |
| Separate watercraft policy | Recommended for higher-value boats | Recommended for higher-value boats | Recommended for higher-value boats |
| Watercraft liability coverage | Limited/subject to policy | Limited/subject to policy | Limited/subject to policy |
Don’t Let Your Boat Outrun Your Coverage
Your boat may be one of your biggest recreational investments. The last thing you want is to discover after an accident, theft, or covered loss that your homeowners policy only provides a fraction of its value.
If your boat is worth more than $1,500—or even $2,500—it’s worth having a conversation about a dedicated watercraft policy.
At Middle Creek Insurance, we can review your current homeowners coverage, discuss your boat’s value and how you use it, and help you determine whether a separate watercraft policy makes sense.
Not enough coverage? Let’s talk about protecting the full value of your watercraft—and adding liability coverage, too.
This article is for educational purposes only. Actual coverage varies by insurance carrier and policy. Please refer to your policy for specific coverage, exclusions, conditions, and limits.